


 by
The 2027 Economic Package does not introduce new federal taxes on purchasing a home, nor does it regulate real estate market prices in Mexico. However, it does redefine the critical macroeconomic variables that determine the viability of any property investment: interest rates, developers’ cost of capital, and currency exchange parity.
Table of Contents
Are Taxes Increasing on Property Purchases in 2027?
The short answer is no. The federal government’s budget proposal does not include new taxes on real estate acquisitions or general rate increases across existing categories. The tax strategy is primarily focused on audits, combating evasion, and tightening corporate tax deductions.
For a buyer or investor, it is essential to distinguish between federal Economic Package policies and the standard tax liabilities inherent to real estate transactions:
- Property Acquisition Tax (ISABI): This is strictly a municipal tax (for example, 4% in Solidaridad / Playa del Carmen applicable to transactions closed since December 2025). It does not depend on the 2027 federal fiscal policy.
- Income Tax (ISR) on Capital Gains: The seller retains the primary residence exemption of up to 700,000 UDIs, provided statutory requirements are fulfilled before a public notary.
- Value Added Tax (VAT / IVA): Mexican law maintains an exemption on land and residential construction sales, differing from commercial or hospitality asset transactions.
Closing tax costs will continue to depend on legal structure, asset type, and geographic location rather than a new federal tax in 2027.
The Crucial Fiscal Shift: Developer Financial Health in Pre-Construction
The most profound impact of the 2027 Economic Package directly affects the capital structure and corporate financing of development companies. Real estate developments are typically funded through combinations of equity, pre-sales, bridge loans, and private debt.
For the 2027 fiscal year, substantial corporate tax revisions are proposed:
- Lower Cap on Net Interest Deductions: The deduction cap is reduced from 30% to 20% of adjusted fiscal profit.
- Limit on Tax Loss Carryforwards: The amortization of prior fiscal losses is capped at 50% of current-year taxable income for legal entities with revenues exceeding $50 million MXN.
Why Does This Matter for Pre-Construction Buyers?
For heavily leveraged developers, debt becomes fiscally more expensive. While this does not automatically trigger price hikes across the board, it introduces a vital underwriting metric:
An aggressive pre-sale discount is not always an investment opportunity; often, it signals an urgent need for operating liquidity.
In 2027, auditing a developer’s balance sheet, land ownership status, and construction execution history is just as important as evaluating floor plans or lifestyle amenities.
Public Deficit, Banxico, and Mortgage Rate Trajectories
Official projections target an annual inflation rate near 3% and 28-day CETES benchmark yields around 6% by year-end 2027. While this suggests monetary easing by Banco de México, it will not automatically or immediately translate into cheaper mortgage financing.
The projected public deficit (Public Sector Borrowing Requirements at 3.9% of GDP) and public debt near 55% of GDP indicate significant government capital demand. Because mortgages are originated over 10, 15, or 20-year horizons, commercial lenders price in sovereign funding costs and long-term risk premiums.
The Cost of Waiting: On a $3.5 million MXN 20-year mortgage, a 100-basis-point spread (from 10.5% down to 9.5%) saves approximately $2,300 MXN per month on principal and interest. Waiting indefinitely for rates to fall can backfire if asset appreciation or rising square-meter costs outpace those financing savings.
The Currency Factor (USD/MXN) in the Riviera Maya and Resort Markets
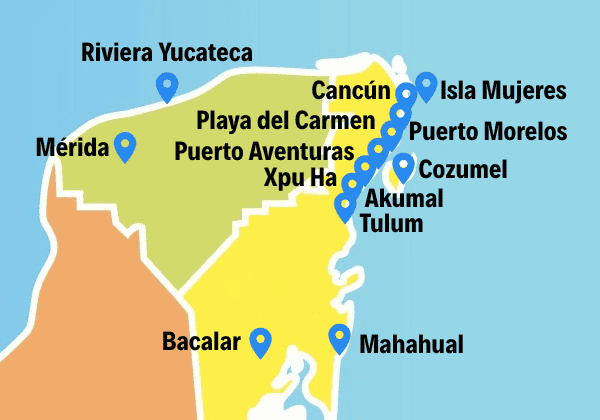
Using a budgetary baseline around $18.00 MXN per USD, the exchange rate creates a dual dynamic across international destinations like Playa del Carmen, Tulum, and Cancun:
1. Entry-Level Purchasing Power
For dollar-denominated capital, a favorable exchange rate lowers the acquisition cost of assets priced in pesos. A $6,000,000 MXN property represents roughly $352,941 USD at $17.00 MXN/USD, but drops to approximately $333,333 USD at $18.00 MXN/USD.
2. Exit Returns and Vacation Rental Yields
True wealth creation depends on the baseline currency used to measure returns. If a peso-denominated property gains 10% in local capital appreciation, but the Mexican peso undergoes a corresponding depreciation against the dollar over the holding period, net equity appreciation in USD can be neutralized.
Furthermore, developments relying on imported finishes (elevators, specialized HVAC, imported glass) face increased construction expenses if the peso weakens, impacting eventual replacement values and pricing structures.
Net Yields vs. the Risk-Free Benchmark (CETES)
With liquid sovereign paper (CETES) projected near 6%, standard marketing claims of “guaranteed returns” or an “8% gross ROI” fall short of institutional underwriting standards.
To justify liquidity constraints and operational risk, real estate assets must deliver a superior Net Operating Income (NOI) after factoring in:
- Condo and HOA maintenance fees.
- Property management and booking platform commissions.
- Provisions for vacancy and furniture replacement reserves (FF&E).
- Property taxes (predial) and operational fiscal obligations.
Defensible property investment rests on the proven convergence of net operating cash flow + disciplined capital appreciation over the medium term.
Checklist: 6 Underwriting Questions for Real Estate Investors in 2027
Before committing capital to pre-construction or immediate-delivery inventory, verify the following:
- What currency governs the purchase contract? Clarify whether the transaction is locked in fixed MXN, fixed USD, or tied to construction index adjustments.
- What is the true Total Cost of Acquisition? Account for purchase price, municipal ISABI, public registry fees, notary disbursements, and bank trust (fideicomiso) setups for foreign nationals.
- How financially resilient is the developer? Review unencumbered land titles, past delivery performance, self-funding equity, and overall reliance on pre-sale cash flow.
- What is the realistic Net NOI? Model conservative occupancy bands and actual operating overheads rather than theoretical maximum yields.
- In which currency is your target return measured? Strong local-currency gains may present a different performance profile when evaluated against long-term USD benchmarks.
- What is the exit strategy? Identify whether target resale liquidity relies on local end-users, relocations, or international secondary buyers.
Conclusion: Strategic Capital Allocation with Institutional Backing
The 2027 Economic Package does not present a binary choice between buying or waiting; it calls for institutional underwriting standards. The market will reward master-planned locations, well-capitalized developers, and net yields supported by verifiable underlying fundamentals.
At Plalla Real Estate, we analyze every property through an asset-management lens: evaluating acquisition pricing, contract currencies, capital costs, net yields, and developer solvency in pre-sales.
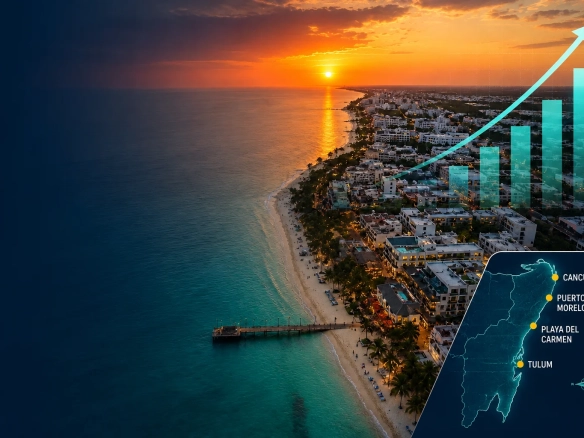
Whether your objective is capital diversification or acquiring premium condos, residential lots, or resort developments in Playa del Carmen, Tulum, Cancun, and the Riviera Maya, Plalla Real Estate guides you through every transaction phase to maximize long-term equity growth and safe, transparent yields.
Connect with an advisor at Plalla Real Estate to evaluate your Riviera Maya investment options
Editorial Note: The 2027 Economic Package was submitted to the Mexican Congress on September 8, 2026, and remains subject to the legislative approval process. Fiscal provisions analyzed may be adjusted prior to final enactment. Financial examples provided are illustrative and do not constitute individualized legal, tax, or financial advice.
Join The Discussion